Will J.B. Hunt’s insurance-cost laden Q4 be taken in stride by investors?
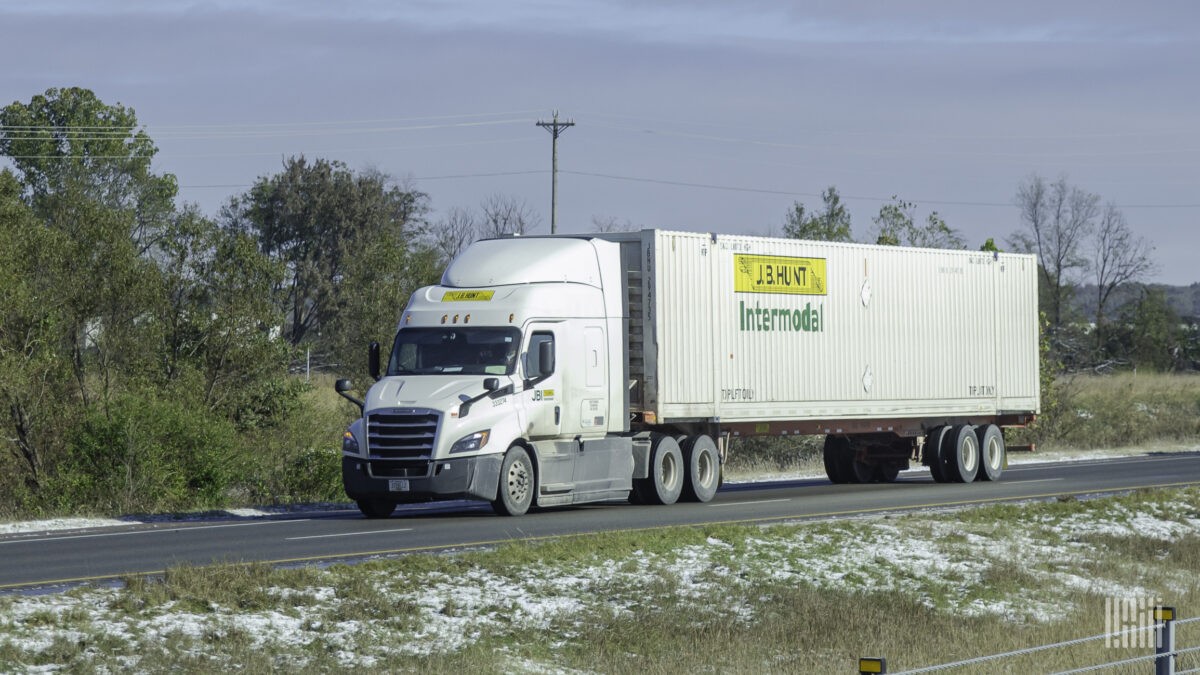
Management from J.B. Hunt Transport Services called out cost pressures on multiple fronts several times on a Thursday evening call with investors. Insurance costs were the most notable reason for a headline miss to fourth-quarter expectations.
J.B. Hunt (NASDAQ: JBHT) reported headline earnings per share of $1.47 for the fourth quarter, which was below the consensus estimate of $1.75. However, the period included $53.4 million in incremental pre-tax charges tied to elevated premiums and the expectation of much higher per-claim payouts. Excluding the 43-cent insurance headwind, EPS would have been $1.90.
The true-up was larger during the 2022 fourth-quarter as the company recorded a $64 million charge tied to incremental reserve adjustments for prior casualty claims, which produced a 46-cent hit to that period.
“Given that the majority of motor carriers in the industry carry only $1 million in coverage, just above the legal minimum of $750,000 in coverage, it’s the larger carriers who bear the brunt or disproportionate share of the escalating insurance and claims cost,” said CEO John Roberts. “And ultimately, these inflationary costs get passed on to customers and consumers.”
Roberts said the number of claims above $1 million jumped 867% from 2010 to 2018. J.B. Hunt’s premiums resetting in 2024 have been 50% to 60% higher despite the company’s numerous safety and risk-mitigation initiatives.
The company also had a $15 million increase in losses on equipment sales during the quarter, which was a 12-cent headwind. Higher interest expense was a 3-cent detractor as net interest expense increased 46% year over year (y/y) with the company’s debt load increasing by 25% in comparison. A lower tax rate compared to last year was a 14-cent tailwind. These items were included in the $1.90 number.
Source: freightwaves.com