US container imports robust in February; inbound volume forecast dicier
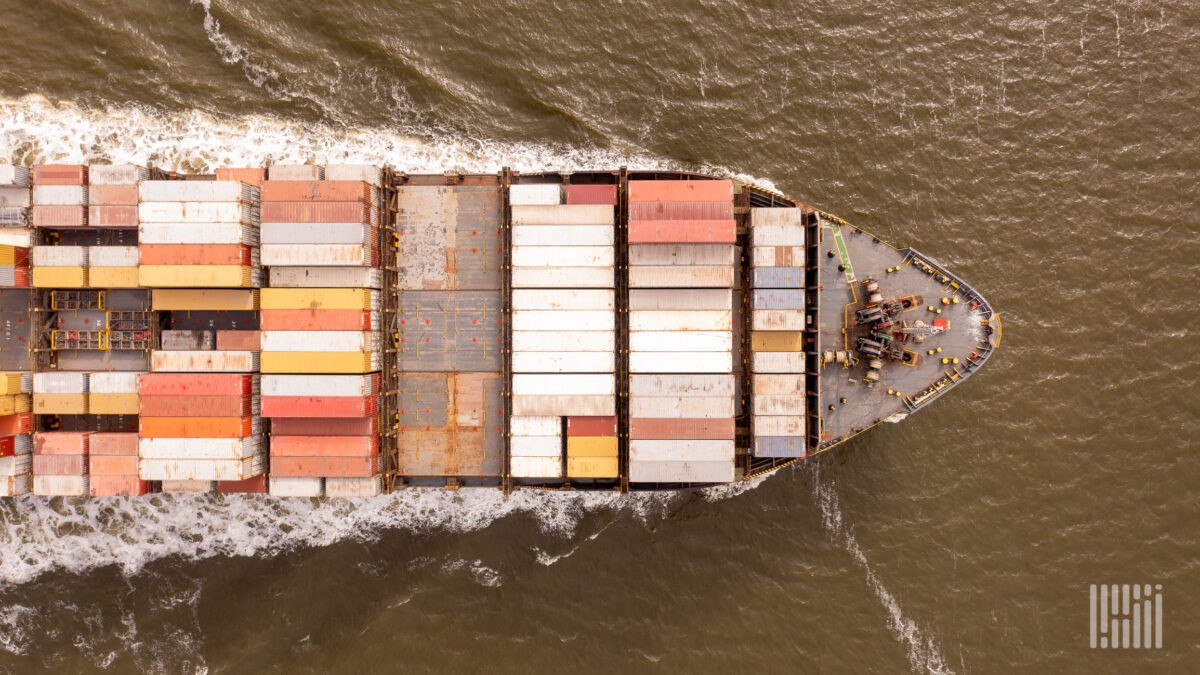
February’s U.S. container import volumes decreased 6% from January — a better-than-expected performance as the sector enters its slow season. But other signs point to potential softness in domestic freight in March and April.
The 2.14 million twenty-foot equivalent units imported in February represent a 23.3% year-over-year increase, according to the latest monthly report from supply chain intelligence firm Descartes. That growth is real, but it isn’t quite as dramatic as it seems.
Last year, the Chinese Lunar New Year began Jan. 22. Holiday festivities include eight days off from work, which causes a temporary shutdown in the country’s manufacturing sector. This means the effect on imports would have filtered into the February 2023 data. This year, meanwhile, the holiday began Feb. 10, which effectively pushed the dip into March.
Adjusting for Lunar New Year by comparing only the first 15 days of February, the annual U.S. import growth rate stands at approximately 13%, per Descartes. This adjustment provides a clearer view into the underlying trade flows, and it’s another positive sign of post-pandemic growth.
Unfortunately for domestic transportation providers, another indicator is showing signs of potential softness in ocean cargo for March and April. Namely, SONAR’s Inbound Ocean TEUs Volume Index (IOTI.USA) has seen its largest Lunar New Year-influenced drop, peak to trough, in more than five years.
Source: FreightWaves SONAR, Inbound Ocean TEUs Volume Index, seasonal.
The annual imports cliff
IOTI.USA free-falls around this time every year. It tracks daily booked ocean container volumes (in TEUs) from specific origins, based on the cargo’s estimated date of departure. It’s averaged over a 14-day period and indexed to a baseline of 10,000, as of Aug. 1, 2020. Each lane’s value contributes to this aggregate baseline.
What’s notable about the drop this year is how steep it was. From the most recent high on Feb. 7 to the most recent low on Feb. 27, the index slipped more than 40%. For comparison, the decline last year was about 30%. In fact, the closest the index has come to this in the past six years is about 35% in 2019, when the U.S.-China trade war was in its early period of escalations.
RELATED: As US-China relations worsen, expect supply chain chaos
This is a bitter pill for carriers, as it suggests the domestic freight market could be softening as the first quarter closes and the second begins.
It is worth noting that IOTI.CHNUSA, which tracks confirmed bookings specifically on the China to U.S. lane, logged a roughly equivalent Lunar New Year cliff in 2023. As carriers might remember, that contributed to volume weakness that further eroded their pricing power and paved the way for a dismal Q2. In May 2023, spot rates hit their lowest point of the current freight downturn.
Source: freightwaves.com